In Focus
GFF 2026 spotlighted agentic UPI payments, sovereign AI and tokenised assets
These innovations signal a shift towards intelligent, programmable financial services
The real test is turning them into trusted, scalable businesses
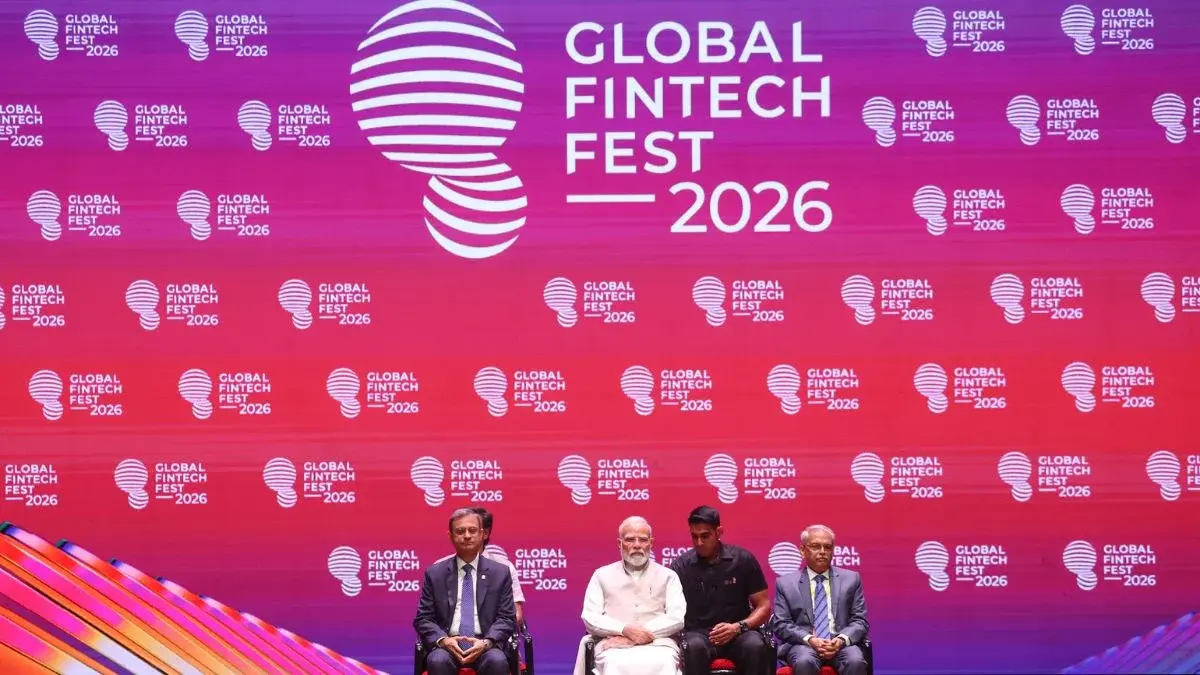
“Technology can distribute a service, but it cannot distribute responsibility,” RBI Deputy Governor Shirish Chandra Murmu said at GFF 2026. That may be the best way to understand what unfolded in Mumbai between September 8 and 11.
The shift was visible across Global Fintech Fest 2026, which drew more than 100,000 attendees, 8,500 institutions, 350 exhibitors, 500 investors and over 1,200 speakers.
India’s first fintech wave focused on moving money faster and bringing more people into the digital economy. The next wave is asking users to delegate financial decisions to software, letting AI resolve complaints, assess credit, and in some cases, make payments on their behalf.
Prime Minister Narendra Modi put the challenge plainly, “Now the challenge before us is how to turn these possibilities into real impact.”
AI Agents Are Getting Closer to Users’ Money
Amazon Pay introduced Smart Wallet, which allows AI agents to make UPI payments for users, initially when booking flight tickets. The company plans to extend these agentic UPI payments to additional merchants and use cases.
BharatPe launched an AI assistant for merchants that connects with more than 60 live systems. It can handle complaints and chargebacks, follow up on requests, and recommend products based on a merchant’s history. “With BharatPe Agentic AI, we are moving beyond answering questions to helping merchants get things done,” CEO Nalin Negi said while announcing the service.
Perfios demonstrated AI agents for credit assessment, while other fintech product launches focused on automated underwriting, compliance, customer support and fraud detection. The breadth of products documented showed how quickly agentic AI has moved from presentation slides to product roadmaps. But giving AI the ability to act introduces risks that a conventional chatbot does not.
Unlike a poor chatbot response, an agentic payment error can cause real financial harm. Agentic UPI will therefore require narrow permissions, spending limits, clear transaction records and easy consent withdrawal, with human confirmation for higher-risk transactions.
UPI Wants to Become More Than a Payment System
UPI remained the center of attention at GFF 2026, but this year’s conversation was not just about processing another record number of transactions.
According to the government’s GFF 2026 background paper, UPI processed 23.66 billion transactions worth $311.4 billion in July 2026. By August, monthly volume had crossed 24 billion transactions. The network was connected to 741 banks and operated in 11 countries. The latest UPI innovations are designed to expand that reach.
NPCI showcased UPI Tap & Pay, which brings contactless payments to compatible NFC terminals. It also introduced FiMI Banking, a compact sovereign AI model designed for Indian retail-banking applications. NPCI is working with HDFC Bank on the model and plans to release benchmarks that institutions can use to test banking agents for safety and appropriate behaviour.
PhonePe and Visa announced Tap to Pay, Cross Border Scan to Pay and Smart Accept. The products combine contactless transactions, international QR acceptance and payment tools aimed at smaller merchants.
Bharat Connect also soft-launched multicurrency foreign-exchange services, initially supporting the euro, pound, Canadian dollar, Swiss franc and UAE dirham.
These UPI innovations point to a broader ambition: transforming UPI from a domestic money-transfer rail into a platform for financial services and cross-border commerce. “Now we can make our own rules and standards and connect them with the world,” Modi said.
India’s Commerce Secretary suggested that the country’s fintech exports could eventually grow from about $8 billion to between $60 billion and $80 billion. India will have to connect its infrastructure with other national payment networks while proving that the system is secure, reliable and commercially sustainable.
Tokenized Assets Meet an Old Problem: Liquidity
Tokenization also offered another glimpse of where India wants financial infrastructure to go next.
Demat 2.0, a regulated pilot involving RBI, SEBI and market infrastructure institutions, allows corporate bonds to be represented as digital tokens. The system links those bonds with wholesale central bank digital currency so that the asset and payment can settle together.
In theory, that could reduce settlement risk, limit reconciliation work, and automate interest and redemption payments through smart contracts.
Corporate bonds still need buyers, price discovery and an active secondary market. Tokenization does not remove an issuer’s credit risk or guarantee that investors will trade the asset. Demat 2.0’s success will therefore depend less on the number of bonds issued during the pilot and more on whether it generates liquidity, lowers costs and attracts a broader range of investors.
Maharashtra’s plan to explore blockchain-based tokens for land and other immovable assets faces a similar reality. Putting ownership information on a digital ledger could improve traceability, but it cannot compensate for unclear titles, contested claims or weak dispute resolution.
GFF’s Biggest Challenge Exists Outside the Venue
GFF 2026 has become one of the world’s largest fintech gatherings. But the Indian industry still lacks some surprisingly basic infrastructure.
There is no single comprehensive registry of active fintech companies. Startups and regulated institutions can take months to negotiate. Young companies may have promising technology but struggle to find customers, banking partners and sufficient time to test their models.
India also lacks a permanent global showcase through which international institutions can discover and evaluate the companies that appear at GFF. As ETBFSI observed, the fest now has an opportunity to become more than an annual networking and content event.
The Bottom Line
The impact of GFF 2026 is not determined by who attended or the number of announcements made on stage. It is about the decisions that were made impacting the future of Fintech.
Do agentic UPI payments expand without weakening user control? Does FiMI Banking become a credible AI foundation for Indian banks? Do tokenized bonds develop an active market? Do partnerships announced at the fest result in products that people actually use? Can Indian fintech companies turn international attention into durable exports?
India’s first fintech breakthrough made digital payments ordinary. Its next must make intelligent and programmable finance dependable. As Murmu said, “Potential without trust produces experimentation. Potential with trust produces impact.”
For GFF 2026, the experiments are already underway. Now they have to prove they can become businesses, infrastructure, and services that users are willing to trust with their money.